There are certain times in life when money can be in short supply and the proverbial belt needs tightening. Usually, this is the case as a student and early on in your career but disposable income can be tight in mid-life too; the arrival of a family coupled with mortgage debt being one example.
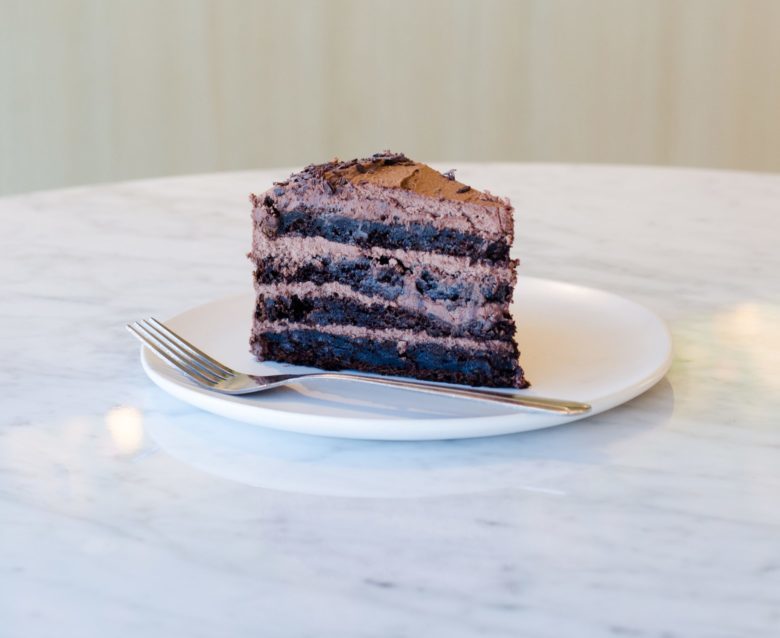
The same questions matter when you are planning retirement. Which costs must you cover, which make life enjoyable, and which could you change if you needed to? Thinking of your spending as a layer cake can help you put those choices in order.
For many, there is never enough money to go around, possibly because earnings potential is limited yet the cost of living continues its continuous march ever upwards.
For others, the lifestyle grows to match increased earnings as careers progress. This is what psychologists refer to as hedonic adaptation or hedonic creep. “I’ve got more money, so I’m going to enjoy it” is an understandable but perhaps short-term mindset; I know of a large number of people who earn well but seem to have little leftover at the end of the month.
What cutting back taught me
Sometimes, a period of penury is a result of career and lifestyle choices. For my wife and me, this happened when I chose to leave the sanctuary of employment to set up this business, which happened to coincide with her redundancy and the birth of our second child.
It wasn’t an easy time; you don’t fully appreciate the regular pay cheque until it is gone but it was intended so it was not something we were going to complain about. We also took the steps to make sure we had sufficient cash reserves in advance so the loss of earnings could be absorbed to some extent.
What we have found to be an unexpected benefit to cutting back hard on our lifestyle was that it has helped to understand what we value and what were actually costs that were habitual and repeated but not valued.
Naturally, there are expenses we couldn’t avoid: the mortgage, utility bills, council tax and food for example. But even the food bill we managed to trim extensively by reducing our meat consumption (a win double for the environment and our diet too).
Other expenses we removed (Sky TV, holidays); avoided (Amazon Prime, because who needs anything that quickly? And, free deliveries are often quicker than expected); reduced (streaming services and not going out quite as much) but others we retained because they were nominal (Netflix) or were important to us (periodic socialising and clubs and activities for the children).
Build your spending layer by layer
When the time came that our disposable income started to rise again we had a good foundation from which to work out what our short, medium and long-term priorities are and allocate our money accordingly. So, like the layers of a cake our spending was built up layer by layer:
- Essential expenditure,
- Short-term discretionary allowances for things we needed or valued,
- Saving for the long-term priorities (for example, retirement and paying off the mortgage),
- Saving for short to medium-term priorities (for example, having a regular saving habit for annual holidays so that we don’t need to find the money from savings when we needed to pay for them),
- Treats and other luxuries that were affordable once everything else was catered for.
The really interesting thing is that, once you go through a period of belt-tightening and come out the other side, if you know what is most important to you, the luxuries are of less importance than they would be if money has just steadily increased over the years without any examination of where it was going.
Using the layer cake in retirement
If you are wondering whether your money is being put to the most appropriate use, start with what you actually spend. Look through recent bank and credit card statements. Allow for annual bills and occasional purchases too, rather than treating one quiet month as your normal budget.
Give each item a place in your own layer cake. You might find some spending has become a habit rather than something you value. Equally, a hobby or regular visit to family may deserve a higher place than its price suggests.
Then ask yourself three questions:
- What would I need each month to cover the essentials?
- What would I want to add to make retirement enjoyable?
- Which costs could I postpone or reduce if my circumstances changed?
The answer will be personal. A holiday that is an occasional treat for one household might be a central retirement priority for another. The point is to recognise your choices, not to copy somebody else’s budget.
My article on understanding your lifetime priorities can help you decide which layers matter most. If you are still working, remember that some costs may disappear when work stops, while others may grow. Keep an emergency reserve separate from money already committed to planned spending.
Once you have a budget, compare it with the income you expect to receive, using figures after tax. The remaining gap is what your pensions and savings need to support. My guide to working out how much is enough takes you through that next step. You can also explore spending in the Retirement Lifestyle Calculator.
A clearer picture of your spending gives you something useful to discuss, rather than a vague feeling that retirement might be expensive. If you would like help connecting those numbers with the life you want, please do get in touch.
Photo by Will Echols on Unsplash