We spend our working lives trying to secure our futures while also providing for our immediate wants and needs. We may do some or all of the following:
- Insure our houses against fire and flood, our cars against accidents and theft, and our holidays against cancellations and medical bills.
- Save into pensions and ISAs, building up investments to support our lifestyles when we stop working.
- Keep money in the bank to cover emergencies, perhaps enough to replace the boiler, repair the car or tide us over if our income unexpectedly stops.
- Insure our lives, protect our incomes against illness and take out private medical insurance to cover the cost of treatments.
These are all sensible precautions. After all, financial planning is largely about preparing for a future we cannot predict.
But there’s a problem. However carefully we plan, however many precautions we take and however much money we accumulate, we can’t remove every risk.
Risk Is What’s Left Over
Former financial planner turned author Carl Richards offers one of my favourite definitions of risk:
“Risk is what’s left over after you think you’ve thought of everything.”
We can anticipate a stock market crash, rising inflation, unexpected expenditure or a period of poor health. We can build contingency plans, diversify investments, arrange insurance and hold additional savings.
But what about the things we haven’t considered?
The unexpected combination of circumstances that throws even the most carefully constructed plan off course? Nobody predicted every consequence of the pandemic, just as nobody knows what the next major economic or personal disruption will be.
And this is where financial planning has its limitations. We can make ourselves better prepared for uncertainty, but we cannot eliminate it. Nor should we allow the pursuit of complete financial security to become an end in itself.
A Lesson From the Stoics
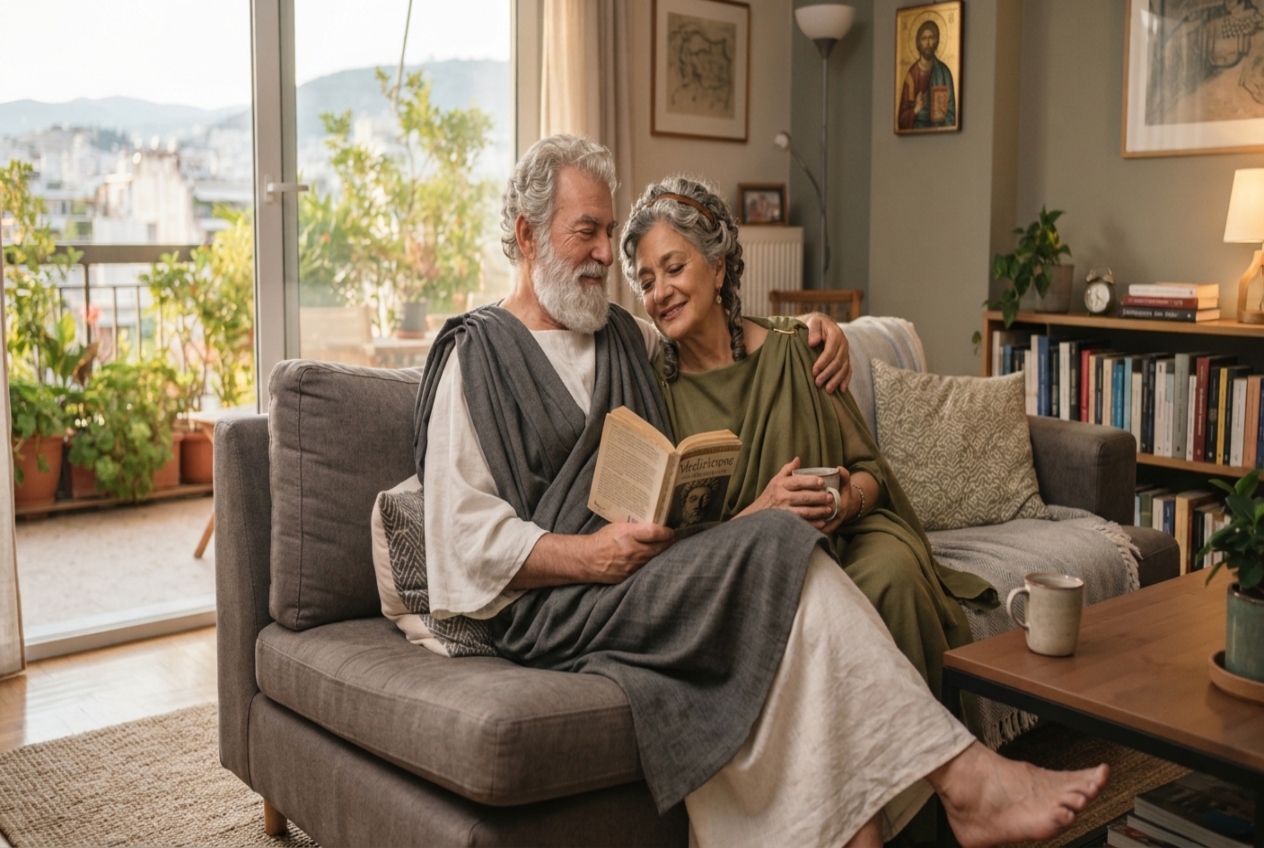
This isn’t a particularly modern dilemma. More than 2,000 years ago, the Greek and Roman Stoic philosophers were grappling with similar questions about uncertainty, security and how to live a good life. One of the central principles of Stoicism is recognising the distinction between what we can control and what we cannot.
As the Greek philosopher Epictetus observed:
“Some things are in our control and others not.”
It’s a simple idea, and two millennia later, rather obvious, but it has relevance to financial planning.
We can control how much we save, how we invest, the insurance we arrange and the decisions we make about spending. We cannot control investment markets, economic conditions, how long we live or every unexpected event that might affect our finances.
That isn’t to say we should abandon planning or simply accept whatever happens. Rather, we should concentrate our efforts on what we can influence and develop the ability to cope with what we cannot.
As Viktor Frankl wrote in his seminal book, Man’s Search for Meaning:
Everything can be taken from a man but one thing: the last of the human freedoms—to choose one’s attitude in any given set of circumstances, to choose one’s own way.
In other words, our last freedom is how we choose to react to any situation.
The Other Side of Financial Resilience
When we think about financial resilience, we tend to think about money.
How much do we have in savings? How secure is our income? Could our investments withstand a prolonged market downturn?
These are important questions, particularly as we approach retirement and become increasingly dependent on the wealth we’ve accumulated.
But I think there’s another, often overlooked, aspect of financial resilience.
Could you live a simpler life and still be happy?
Suppose circumstances meant you had to reduce your spending. Perhaps you couldn’t afford the holidays you previously enjoyed, needed to change your car less frequently or had to become more selective about meals out and other luxuries.
Would that fundamentally change how you felt about your life?
For some people, the answer might be yes. Particularly if they’ve spent years working hard to achieve a particular lifestyle, the prospect of giving some of it up can feel like a significant loss.
But there’s a difference between sacrificing the things that make life meaningful and sacrificing some of the comforts we’ve become accustomed to. Enjoying time with family and friends, maintaining relationships, pursuing interests, contributing to our communities and having a sense of purpose needn’t depend on spending large amounts of money.
That’s not to say money doesn’t matter. It does. Having sufficient money to meet our needs and enjoy life provides freedom, choices and peace of mind.
Nor should we downplay financial hardship. There is a world of difference between voluntarily giving up a few luxuries and being unable to afford the essentials, as many in the UK are unable to do.
But perhaps the greatest financial resilience comes from knowing that even if circumstances changed, we could adapt and still lead a fulfilling life.
The Risk of Being Too Cautious
There’s another side to this argument, however.
If we become so concerned about protecting ourselves against every possible eventuality, we risk overlooking what our money is actually for.
I’ve know people approaching retirement who are understandably anxious about spending their savings. After decades of accumulating wealth, the prospect of seeing their capital reduce can be uncomfortable. What if they live longer than expected? What if care costs become substantial? What if investment returns disappoint?
These are legitimate concerns, and they aren’t to be ignored. But what if the holidays are continually postponed, the experiences put off and the opportunities missed because we’re waiting to feel completely financially secure?
There is a risk in spending too much, but there is also a risk in spending too little.
Unlike our savings, time is not a resource we can replenish. The ability to enjoy certain experiences diminishes as we get older, whether through declining health, reduced mobility or changing family circumstances. And that’s something our financial plans need to accommodate.
Making the Most of the Years Ahead
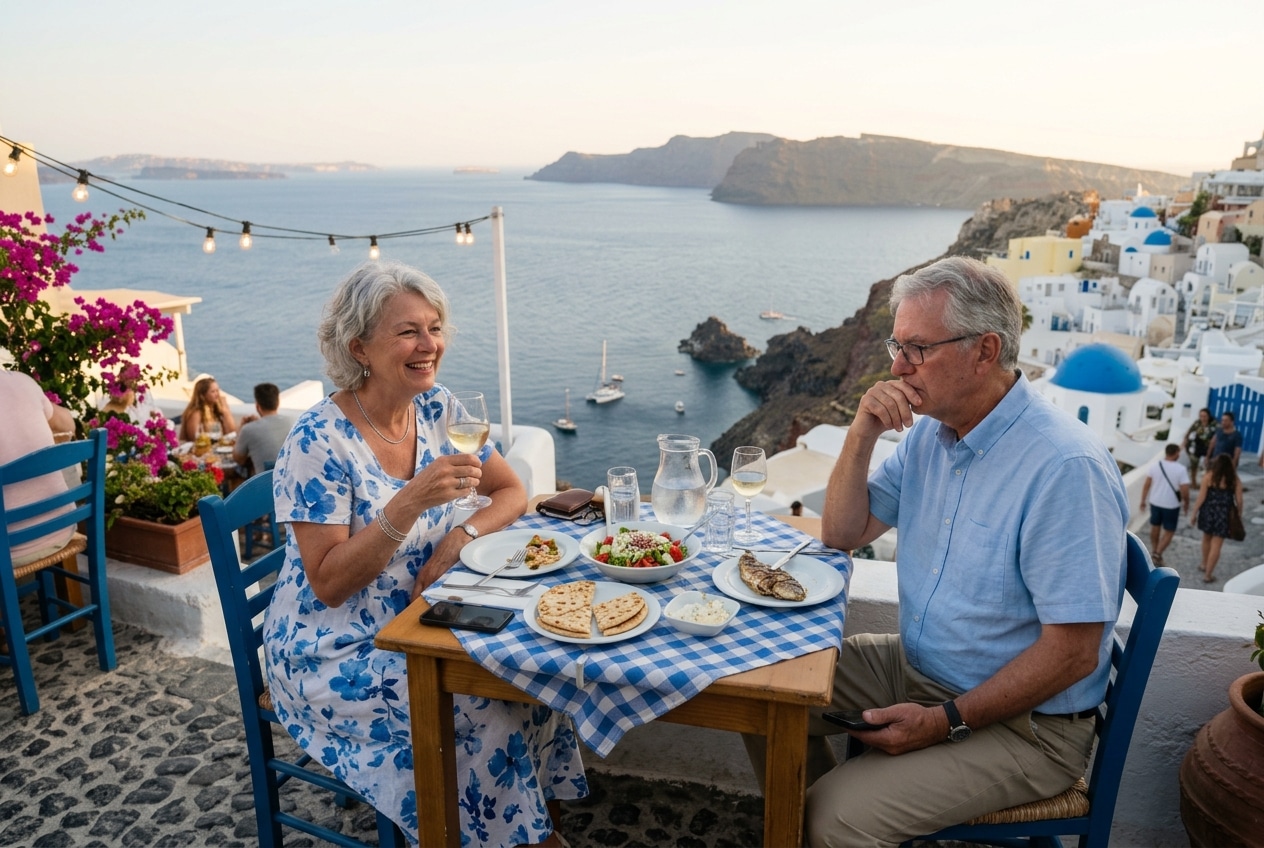
Consider a couple retiring in their early 60s. They’ve worked hard, saved diligently and built up a reasonable level of financial security.
They have a list of things they’d like to do in retirement. Travel to places they’ve never visited, spend longer periods abroad and perhaps take their children and grandchildren on a special family holiday. But they’re also conscious that their savings need to last for the rest of their lives.
One approach would be to limit their spending, preserve as much capital as possible and hope that, eventually, they’ll feel sufficiently secure to start enjoying more of it.
Another would be to recognise that their retirement spending doesn’t necessarily need to remain constant. They might choose to spend more during their 60s and early 70s, when they’re hopefully fit, healthy and able to enjoy travelling and other activities. This would be a deliberate decision, supported by a financial plan that considers the possible consequences.
They would understand that spending more today could mean having less available in later life. They would also need to consider how they would cope with unexpected expenses or disappointing investment returns. But they might decide that’s a trade-off worth making.
Perhaps, by their late 70s or 80s, they’ll be content with a quieter lifestyle. Fewer overseas holidays, more time spent closer to home and greater enjoyment of the simple pleasures of everyday life.
Of course, this isn’t inevitable. Plenty of people remain active well into their 80s and beyond, while others experience health problems much earlier. And nobody should assume that later life will necessarily be cheaper, particularly when care costs are taken into account.
Nevertheless, the principle remains. If this couple eventually need to reduce their discretionary spending, they may be able to look back with considerable satisfaction at the experiences they’ve enjoyed. The places they visited, the things they did together and the memories they created with their family.
They might no longer be able to afford the same lifestyle, but they can still say, “I’m glad we did those things while we could.” That is a rather different form of financial security.
Finding the Right Balance
None of this is an argument for abandoning financial prudence or spending recklessly. It’s about recognising that financial security and enjoying life are not competing objectives. A good financial plan should accommodate both.
We should insure against risks that could cause serious financial harm, maintain adequate reserves, invest appropriately and understand how much we can reasonably afford to spend.
We should also recognise that our future spending needs aren’t necessarily fixed. Some expenditure is essential, while other spending is discretionary and could be adjusted if circumstances required it.
That flexibility has value. Knowing which parts of our lifestyle we could comfortably change gives us greater freedom to enjoy the money we have today.
And perhaps this is where the ancient Stoics still have something to teach us. Wealth is useful because of what it allows us to do, but our sense of contentment shouldn’t depend entirely on retaining it. Financial planning can help us understand the trade-offs, test different scenarios and establish how much uncertainty we’re prepared to accept.
But the final piece of the puzzle isn’t a financial product, an investment strategy or a particularly sophisticated spreadsheet. It’s our ability to adapt.
Ultimately, the objective shouldn’t be to accumulate enough money to guarantee that nothing will ever go wrong. That’s an impossible ambition. It’s to build sufficient financial security to enjoy life, enough flexibility to cope when things don’t go according to plan, and enough perspective to recognise that a meaningful life doesn’t necessarily require maintaining the same standard of living forever.
Perhaps genuine financial freedom isn’t knowing that we’ll always be able to afford everything we want. It’s knowing that, even if we can’t, we can still be content with the life we lead.